Full entitlement
No VA-imposed loan limit.
This does not guarantee a loan amount or lender approval. The lender still reviews your finances, and the property appraisal matters.
Entitlement describes VA’s loan guaranty—not cash available to spend.

Buying, using the benefit again or refinancing starts with understanding your entitlement and the loan requirements. VA determines eligibility; your lender evaluates qualification.
Scheduling opens Calendly in a new tab.
Start here
My grandfather, Claude Edwards, served 23½ years in the U.S. Army and retired as a First Sergeant (E-8). He used his VA home loan benefit to build a home in Anchorage, Alaska, then started a carpet-cleaning business from his garage that served the community for nearly 40 years.
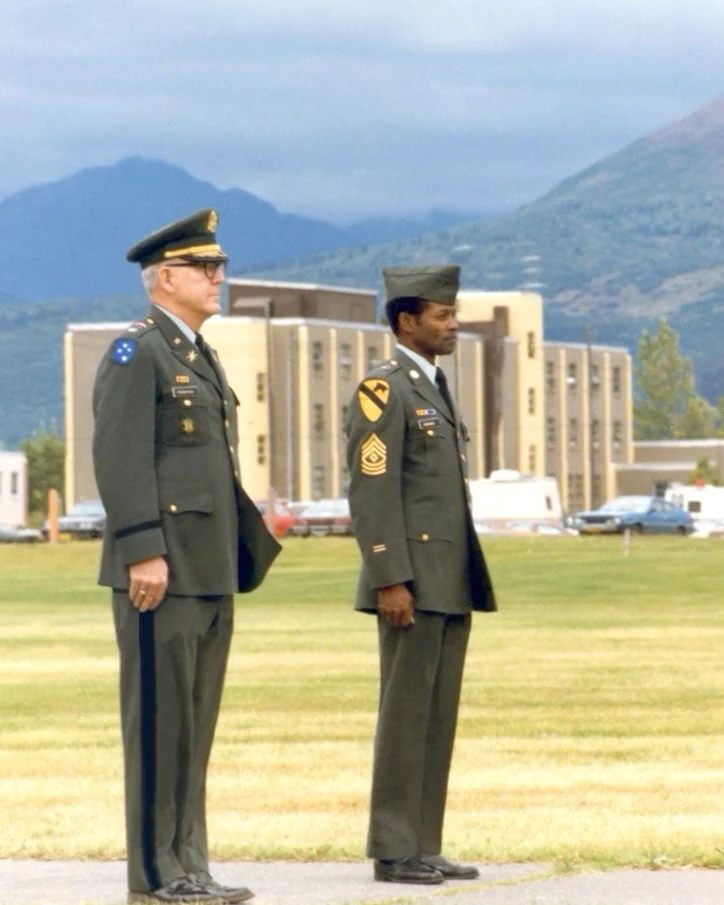
His story shaped the way I see the VA benefit. Homeownership gave him more than a place to live. It became a foundation for entrepreneurship, financial stability and what he built after military service. That’s why helping veterans understand and make the most of the benefit they’ve earned matters to me.
Serving people who served
These branch names acknowledge the audience, not Aaron’s service or credentials. They do not establish eligibility or imply military endorsement.
Using a VA loan once doesn’t necessarily mean you’ve used up your benefit. Depending on your entitlement, you may be able to use a VA loan again, even while keeping a home financed with VA.
Three distinct situations—not steps, scores or approval levels. Your Certificate of Eligibility (COE) is the starting record.
No VA-imposed loan limit.
This does not guarantee a loan amount or lender approval. The lender still reviews your finances, and the property appraisal matters.
Entitlement describes VA’s loan guaranty—not cash available to spend.
Prior use may leave entitlement available.
You may be able to buy again while retaining a VA-financed home. The COE, entitlement already charged and the property’s county loan limit inform what remains.
A down payment may be needed. Lender approval is still required.
Previously used entitlement may be restored.
VA lists these alternative paths, subject to continued eligibility:
Request restoration through VA; it is not a loan approval.
Official guidance: VA eligibility and restoration · VA entitlement and loan limits. Checked September 27, 2026.
A military family PCSing from Washington State to Maryland needed the financing to keep pace with their move. We were clear to close nine days after the loan process began.
For veterans with an existing VA loan looking to reduce their rate or payment when the required benefit and seasoning standards are met.
For eligible veterans looking to refinance their current mortgage and potentially access home equity. The existing mortgage does not necessarily have to be VA.
Confirm eligibility and understand your available entitlement.
Income, assets, debts, credit and what payment makes sense.
Know your realistic buying range and how the VA financing will be structured before making offers.
I look at military housing beyond the transaction itself. That means understanding the VA benefit, preparing before a transition or PCS, and thinking about how housing fits into the financial decisions that come next.
This is not a government website and I am not affiliated with the Department of Veterans Affairs. Entitlement and eligibility are determined by the VA. If you have enough down payment that the funding fee stops making sense, conventional is worth pricing against this. See residential lending or compare loan programs.
Let’s work through your next step. Bring your questions about entitlement, buying again or refinancing.