Your VA home loan benefit

Make sense of your VA benefit.

Buying, using the benefit again or refinancing starts with understanding your entitlement and the loan requirements. VA determines eligibility; your lender evaluates qualification.

The short version: your VA benefit may be usable more than once, VA decides your entitlement, and a lender decides whether the loan fits your finances.

Scheduling opens Calendly in a new tab.

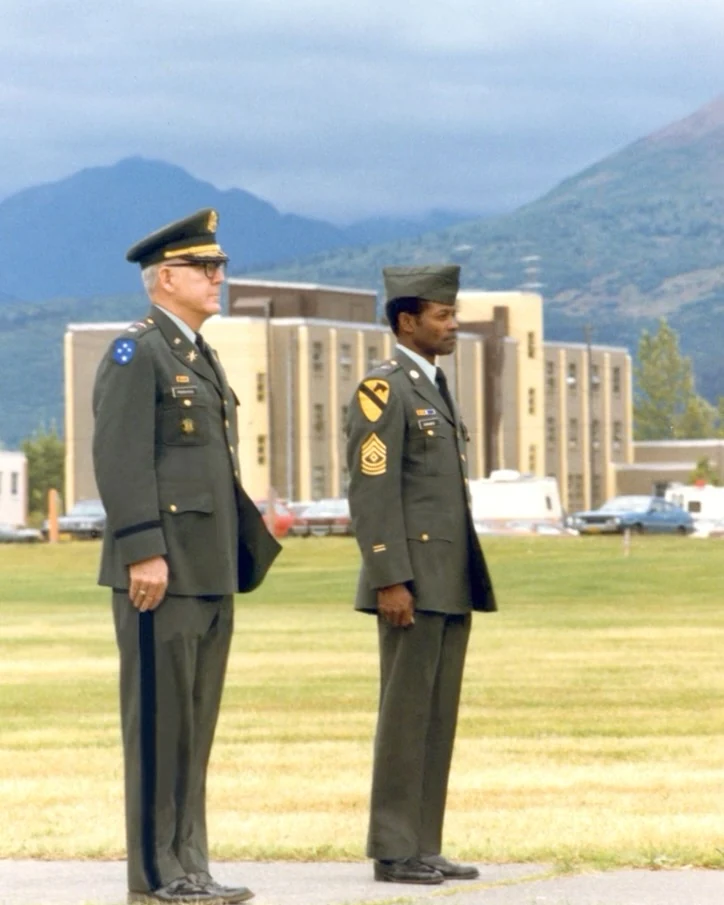
Claude Edwards in U.S. Army uniform, Anchorage, Alaska, 1980s
From Aaron’s family archive.
Claude Edwards · U.S. Army · Anchorage, Alaska · 1980s

Your benefit, understood

What would you like to understand?

Choose a starting point. This explains the benefit; it does not determine eligibility.

Start with the full picture.

Before shopping, connect your available entitlement with your income, debts, cash and a payment you can live with.

VA determines eligibility. The lender evaluates income, credit, occupancy and the property.

Prepare, then shop

  • Confirm your COE
  • Review the full payment
  • Understand your buying range

A COE confirms benefit eligibility, not lender approval.

Entitlement

Used a VA loan before? You may still have options.

Using a VA loan once doesn’t necessarily mean you’ve used up your benefit. Depending on your entitlement, you may be able to use a VA loan again, even while keeping a home financed with VA.

1 · Find yours

Two questions point you to the situation that likely applies.

2 · All three situations

Full, remaining or restored. The bold line in each card is the short answer.

Three distinct situations, not steps, scores or approval levels. Your Certificate of Eligibility (COE) is the starting record.

Full entitlement

No VA-imposed loan limit.

With remaining entitlement, the county loan limit helps set what’s left.

This does not guarantee a loan amount or lender approval. The lender still reviews your finances, and the property appraisal matters.

Entitlement describes VA’s loan guaranty, not cash available to spend.

Remaining entitlement

Prior use may leave entitlement available.

Keeping a VA-financed home can affect what remains available.

You may be able to buy again while retaining a VA-financed home. The COE, entitlement already charged and the property’s county loan limit inform what remains.

A down payment may be needed. Lender approval is still required.

Restoration

Previously used entitlement may be restored.

Remaining entitlement is what’s left; restoration may return what was used.

VA lists these alternative paths, subject to continued eligibility:

  • Sell and repay: sell the prior home and repay its VA loan in full.
  • Assumption with substitution: a qualified Veteran assumes the loan and substitutes their entitlement for the amount originally used.
  • Repay and retain: repay the loan in full while keeping the home, a one-time restoration option.

Request restoration through VA; it is not a loan approval.

3 · Check the source

VA’s own pages, and the record that starts it all.

Official guidance: VA eligibility and restoration · VA entitlement and loan limits. Checked September 27, 2026.

Not sure what you have available? Start with your COE

VA refinancing

Already have a home? Your VA benefit may still have options.

IRRRL

For veterans with an existing VA loan looking to reduce their rate or payment when the required benefit and seasoning standards are met.

VA cash-out refinance

For eligible veterans looking to refinance their current mortgage and potentially access home equity. The existing mortgage does not necessarily have to be VA.

Prepare, then shop

Three things before you shop.

1

Get your COE

Confirm eligibility and understand your available entitlement.

2

Review the full financial picture

Income, assets, debts, credit and what payment makes sense.

3

Understand the benefit before shopping

Know your realistic buying range and how the VA financing will be structured before making offers.

Need help getting your COE?

A recent VA purchase

9 days

Washington to Maryland. Clear to close in 9 days.

A military family PCSing from Washington State to Maryland needed the financing to keep pace with their move. We were clear to close nine days after the loan process began.

One client’s experience; timing and outcomes vary with the file.

Beyond the VA loan

The benefit is one part of the housing picture.

I look at military housing beyond the transaction itself. That means understanding the VA benefit, preparing before a transition or PCS, and thinking about how housing fits into the financial decisions that come next.

Qualification and affiliation

This is not a government website and I am not affiliated with the Department of Veterans Affairs. Entitlement and eligibility are determined by the VA. If you have enough down payment that the funding fee stops making sense, conventional is worth pricing against this. See residential lending or compare loan programs. Buying near a Georgia base? See zero-down options by installation.

Let’s work through your next step.

Bring your questions about entitlement, buying again or refinancing.